Does Mobile Home Insurance Cover Mold in Florida?

Moisture meter beside a small water stain in a mobile home

Mold in a Florida mobile home can follow a roof leak, plumbing failure, storm opening, appliance leak, flood, condensation, or long-running humidity problem. Whether mobile home insurance may address any part of the damage depends on what caused the moisture, how suddenly it happened, what the policy excludes, and whether the contract places a separate limit on fungi, wet rot, remediation, or testing.

There is no safe universal answer to β€œis mold covered?” A policy may respond to certain damage from a covered water event while limiting or excluding mold-related costs. It may also exclude the event that introduced the water. Start with the cause and the timeline, then read the form and endorsements.

Insurance Reviews the Cause Before the Mold

Property claims generally begin with the event that produced direct physical damage. A sudden accidental discharge from an insured plumbing system may be treated differently from rain entering through a deteriorated roof over many months. Floodwater rising from the ground is typically handled under a separate flood policy, if one exists, rather than ordinary mobile home coverage.

The same visible mold can therefore lead to different claim evaluations. An adjuster may examine the failed component, water path, staining, maintenance history, weather timing, prior repairs, and how quickly the homeowner acted. Photographs and a clear chronology are more useful than guessing which species is present.

Sudden Water and Long-Term Moisture Are Different

A sudden leak is an identifiable event at a particular time. Long-term seepage, repeated leakage, condensation, high humidity, ground moisture, or unrepaired exterior openings develop over time. Many policies distinguish between those patterns and contain maintenance, wear, deterioration, or repeated-seepage exclusions.

Even when the initial water damage is covered, the policy may cap mold investigation, removal, treatment, tear-out, or additional living expense related to fungi. Some limits apply across the entire policy period. Others depend on whether mold resulted from a covered cause. Only the actual form can answer which wording applies.
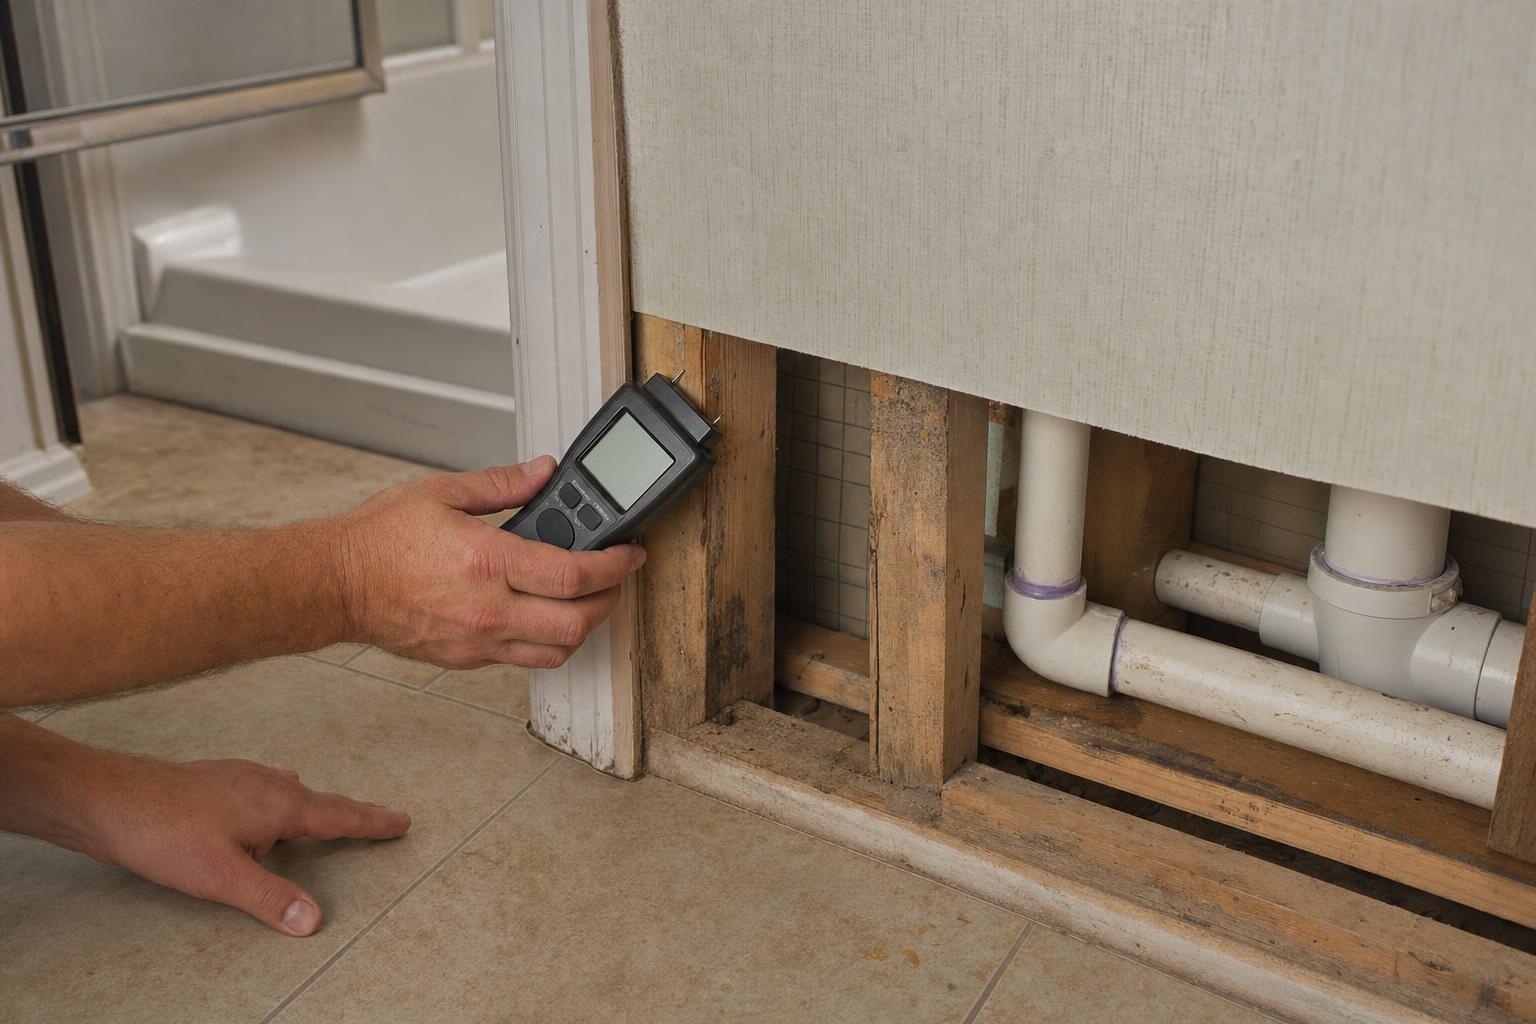
Moisture inspection near a mobile home wall after a small plumbing leak

Florida Humidity Does Not Establish Coverage

Warm humid air can condense on cool surfaces, especially where air conditioning, ductwork, insulation, skirting ventilation, or air sealing is not working as intended. Florida conditions make moisture control important, but climate alone does not prove that a loss is insured. Insurance is not a substitute for ventilation, routine inspection, prompt repair, and safe humidity management.

The U.S. Environmental Protection Agency’s guide to mold and moisture emphasizes controlling moisture and drying wet materials quickly. Its health and cleanup guidance does not interpret an insurance policy, but it helps explain why prompt action matters.

Roof Leaks Require a Cause Analysis

If wind or another covered event creates a sudden roof opening and rain enters, the resulting evaluation may differ from water entering through worn seals, failed coating, corrosion, or deferred maintenance. The roof material, age, installation, prior condition, and storm evidence all matter. A policy might treat damage to the roof, interior water damage, and mold remediation under different provisions.

Do not climb onto a wet or damaged mobile home roof. From a safe location, photograph missing material, impact marks, ceiling stains, and the surrounding area. Arrange a qualified inspection and preserve any emergency-repair invoice. Our article on mobile home roof damage explains why the source of damage matters.

Plumbing and Appliance Leaks Need Prompt Action

Shut off the local fixture or main water supply if it is safe and you know how. Move undamaged property away from the wet area, use reasonable emergency drying measures, and report a potentially covered loss promptly. Do not energize wet electrical equipment or enter an area with a sagging ceiling, sewage, or structural instability.

Keep the failed hose, fitting, or part if it can be preserved safely. Record when the leak was discovered, where water travelled, and what emergency work was performed. Review our guide to water and plumbing damage for additional distinctions between sudden escape of water, backups, flood, and maintenance problems.

Flood and Storm Surge Need Separate Attention

Standard mobile home policies commonly exclude flood, including storm surge and surface water. Flood coverage is purchased separately and follows its own definitions, limits, and claims process. Mold or mildew resulting from floodwater may also be subject to the flood policy’s terms and the homeowner’s ability to take reasonable mitigation steps.

If water source is uncertain after a storm, document high-water lines, openings, roof damage, and the order in which conditions occurred. Avoid making a final cause statement before qualified inspections. More than one source can affect the same room, and each policy may need notice.
Dehumidifier and air mover drying a mobile home interior after water removal

What Mold-Related Expenses Might Be Reviewed?

A claim can involve several expenses: locating the moisture source, opening building materials, drying, cleaning, removing damaged material, testing, containment, rebuilding, personal-property damage, and temporary relocation. A policy may treat each differently. A remediation recommendation or contractor invoice does not by itself establish that every line item is covered.

Ask whether the policy has a fungi or mold endorsement, a sublimit, testing requirements, approved-vendor provisions, or notice duties. Ask how additional living expense works if the home cannot be occupied and whether that benefit depends on a covered loss. Never rely on a verbal description when the endorsement can be provided.

Document Without Spreading Contamination

Take overview and close photographs before removing material, but avoid disturbing a large affected area. Do not paint over growth or apply chemicals that could complicate inspection. For extensive contamination, sewage, significant health concerns, or damage inside walls and HVAC components, seek qualified professional guidance.

Create a timeline with the first sign of water, discovery of visible growth, weather events, calls, inspections, and emergency measures. Save receipts and estimates. If property must be discarded for safety, ask the insurer about documentation first when practical, and photograph identifying details without exposing yourself to unsafe material.

Prevention and Coverage Review Work Together

Inspect roof penetrations, plumbing connections, water-heater pans, supply hoses, windows, exterior sealants, skirting, and the underside of the home as appropriate. Keep gutters and drainage paths clear, use bathroom and kitchen ventilation, service air conditioning equipment, and respond to musty odours or staining early. These steps reduce damage but cannot guarantee a mold-free home.

At renewal, ask a licensed agent to point out water, seepage, flood, mold, fungi, wet-rot, ordinance, and loss-of-use provisions. Bassine’s mobile home insurance and manufactured home insurance pages provide a starting point for the broader coverage discussion.

Frequently Asked Questions

Is mold from a leaking pipe covered?

It may depend on whether the leak was sudden, accidental, covered, and reported promptly, plus any mold exclusion or sublimit. Long-term leakage may be treated differently.

Does mobile home insurance cover mold after a hurricane?

The answer depends on how water entered and which cause produced the damage. Wind-created openings, flood, storm surge, and pre-existing leakage can fall under different terms or policies.

Will insurance pay for mold testing?

Testing may be limited, excluded, or included only when tied to a covered loss and handled under policy procedures. Confirm authorization and limits before ordering non-emergency work.

Should I clean mold before an adjuster sees it?

Take reasonable steps to prevent further damage and protect health, but document conditions first when safe and contact the insurer promptly. Large or hazardous areas call for professional advice.

For a policy-specific review of mold and water-damage provisions, contact Bassine Insurance Agency. A licensed agent can explain available forms and limits; only the insurer’s claim review can determine whether a particular loss is covered.

What Is Ordinance or Law Coverage for Florida Mobile Homes?

Florida manufactured home exterior during a permitted siding repair

Repairing or rebuilding a mobile or manufactured home after a covered loss can involve more than replacing what was damaged. Current building, installation, electrical, wind, floodplain, or community requirements may call for additional work that was not part of the older home. Ordinance or law coverage is the part of a property policy that may help with certain added costs caused by enforcing a current code or ordinance.

The name sounds technical, but the practical question is simple: if a covered loss damages the home, would the policy address only like-for-like repairs, or could it also address eligible code-required upgrades? The answer depends on the policy form, endorsements, limits, cause of loss, and how local officials treat the project. Coverage should never be assumed from the phrase alone.

Why Code Costs Can Appear After a Loss

A home may have complied with the rules in effect when it was installed. Years later, a permit for substantial repair or replacement may bring parts of the project under newer requirements. Those requirements can affect tie-downs, electrical equipment, stairs, accessibility, energy performance, elevation, wind resistance, or the way an addition connects to the home.

The damaged material and the code-required work are not always the same expense. For example, a storm may damage one section, while a building official requires related work elsewhere before the permit can close. Standard property coverage often focuses on direct physical damage from a covered cause. Ordinance or law provisions address a different category of expense, subject to the exact contract.

Three Types of Expense Commonly Discussed

Policy wording varies, but ordinance or law protection is often described in three broad parts. One may concern the undamaged portion of a structure when an authority requires demolition. Another may concern the cost to demolish and remove that undamaged portion. A third may concern the increased construction cost required to complete eligible repairs under current rules.

These descriptions are a reading guide, not a statement that a particular mobile home policy includes all three. Some forms combine them, use different names, limit them separately, or exclude certain structures. A declaration page may show only a percentage or dollar limit, so the endorsement and definitions still need review.

Mobile home exterior prepared for a permitted repair in Florida

Mobile Homes Add Installation and Ownership Questions

Manufactured housing can involve federal construction standards, Florida installation rules, local permitting, park requirements, and separately built features. The home itself, an attached screen room, carport, porch, utility shed, and foundation or tie-down system may not all be treated the same way by the policy or the permitting authority.

Ownership also matters. A resident may own the home but lease the lot, while the park owns utilities or shared improvements. Before a loss, identify who owns each structure and who is responsible for code compliance. That information helps an agent understand what property needs to be considered and helps avoid treating a park-owned item as part of the resident’s home.

A Covered Loss Still Has to Trigger the Claim

Ordinance or law coverage generally does not turn an excluded event, maintenance problem, or voluntary remodel into a covered loss. The underlying damage usually must result from a cause covered by the policy, and enforcement of a code or ordinance must create the additional eligible cost. A homeowner who chooses an upgrade beyond what officials require may be responsible for the difference.

Flood presents a separate issue. A mobile home policy may exclude flood, while a flood policy follows its own contract and rules. Requirements tied to substantial damage in a floodplain can be significant. Ask which policy, if any, would respond before assuming that a homeowners endorsement and a flood policy work the same way.

Limits and Valuation Can Change the Outcome

Check whether the ordinance or law limit is a flat amount, a percentage, part of another property limit, or an additional amount. Also ask whether a deductible applies and whether payments depend on completing the work. Replacement-cost and actual-cash-value provisions can affect other parts of the claim even when a separate code expense is involved.

A low limit can leave a gap when demolition, engineering, permitting, and required upgrades accumulate. A higher limit may cost more and still will not cover every expense. The useful comparison is the contract language and limit against the home’s age, construction, location, attachments, and realistic rebuilding constraints.

What to Ask an Insurance Agent

Bring the declarations page and endorsements to the conversation. Ask whether ordinance or law coverage is included, which property it applies to, the limit for each part, and whether attached structures are handled differently. Ask how demolition, debris removal, permitting, professional fees, and code upgrades interact rather than assuming one provision pays all of them.

Describe any additions and updates accurately. A rebuilt porch, enclosed room, roof-over system, shed, carport, or electrical upgrade can change the questions an agent needs to ask. Bassine’s guides to mobile home insurance and manufactured home insurance explain the broader policy context for Florida owners.

Contractor reviewing a Florida mobile home repair area without visible documents

Keep Records Before and After Damage

Maintain photos of the home and each attachment, receipts for permitted upgrades, inspection records, and basic model and installation information. Store copies away from the property or in secure cloud storage. These records do not create coverage, but they can help identify the pre-loss condition and ownership of improvements.

After damage, protect the property from further harm when it is safe, report the loss promptly, and preserve damaged materials until the insurer gives instructions. Before demolition or permanent repair, document the area and obtain written requirements from the building or permitting authority. An estimate should separate direct repair, demolition, debris, and code-required work so each expense can be evaluated under the correct policy provision.

The Florida Building Commission publishes the state building-code resources, but local officials determine the permits and requirements for a particular project. Your insurer, adjuster, contractor, and building department have different roles; a contractor’s estimate does not decide insurance coverage, and an adjuster does not waive permit requirements.

Review Coverage Before a Permit Is Urgent

Ordinance or law questions are easiest to address before storm damage or another loss makes repairs time-sensitive. Review the provision at renewal and after buying an older home, moving the home, adding a structure, or completing a major permitted improvement. Confirm changes in writing and retain the updated declarations and endorsement.

Frequently Asked Questions

Is ordinance or law coverage automatically included?

It depends on the insurer and policy form. It may be included at a limited amount, offered by endorsement, or unavailable for some risks. Read the declarations and endorsement together.

Does it pay for routine upgrades to an older home?

Ordinarily it is connected to enforcement after covered physical damage, not elective remodeling or deferred maintenance. The policy’s trigger and exclusions control.

Does it cover a carport or screen room?

That depends on whether the structure is insured, how it is attached and described, and what the endorsement covers. List additions accurately and ask about each one.

Who decides which code applies?

The authority having jurisdiction determines permit and code requirements. The insurer decides whether resulting expenses meet the policy terms, subject to applicable law and the claim process.

If you want to understand how ordinance or law coverage may apply to your Florida mobile home, contact Bassine Insurance Agency. A licensed agent can review available policy language and limits for your circumstances without promising a claim outcome.